The Honeymoon Fund Deception: Why Cash Is King (and Points Are Its Loyal Subject)
Wedding Registry Strategy For Point Accumulation
You want to feel smart about extracting value from your wedding without looking mercenary about it. Here’s the actual mechanism: a honeymoon fund isn’t about collecting cash for flights and hotels. It’s a point generation engine. Economics calls this “velocity optimization”—maximizing transaction volume per unit of capital. Your guests give you cash. You convert that cash into credit card spend. The credit card spend produces points. The points buy your honeymoon.
Most couples ask guests for cash and then spend it on normal life expenses, which wastes the earning potential entirely. The real move is directing that cash into a specific credit card designed for either travel categories or sign-up bonuses, then immediately using those points for flights and accommodations. This requires intentionality most people don’t execute. You need a dedicated card, a timeline, and a plan to hit minimum spend before your trip.
Converting Gifts Into Accelerated Point Earning
The common advice says “just put your honeymoon expenses on a rewards card.” That’s lazy. You’re leaving money on the table. Here’s what actually works: identify which credit card offers the highest return in your primary spending category (flights, hotels, or both), calculate how much cash you’ll receive from your wedding fund, then front-load that card with gift money converted into direct purchases.
If your wedding fund collects five thousand dollars and your card offers five points per dollar on travel purchases, you’ve just earned twenty-five thousand points before booking anything. Then you layer in your actual honeymoon bookings on the same card. Combine that with a sign-up bonus from opening the card before your wedding, and you’re operating at multiples of what a casual rewards user achieves. The mechanism is simple: time your card opening, concentrate your gift conversion into one card, and hit minimum spend before your trip departure date.
Beyond The Brochure: Deconstructing The Value Of Travel Credit Cards For Your Honeymoon
Sign Up Bonuses Versus Long Term Returns
You want the magic number that makes this whole game feel justified. Here’s the mechanism: sign-up bonuses front-load value to lock you in, but they’re a one-time event. The real math happens after. Most premium travel cards offer 50,000 to 100,000 bonus points on first purchase, worth roughly $500 to $1,500 depending on redemption. This hits hard upfront, but you need to separate the dopamine hit from the actual earning structure.
The ongoing earning rate determines whether you profit or hemorrhage after year two. A card earning three points per dollar on travel and one point per dollar on everything else will generate 30,000 to 50,000 points annually if you spend aggressively. Compare this to your annual fee, usually $95 to $550. If you don’t spend enough to earn points that offset the fee in cash value, you’re negative. Calculate your typical annual spend in bonus categories first. If it doesn’t math out, the sign-up bonus seduces you into paying for a card that doesn’t work for your actual behavior.
The Cost Hidden In Plain Sight
Premium travel cards charge annual fees that nobody honestly discusses. The consensus says these fees “pay for themselves” through perks. That’s incomplete. The card issuer prices those perks conservatively, meaning the fee extracts more value than the benefits deliver in isolation. A $550 annual fee card might include a $300 airline credit, $200 in travel credits, and lounge access. On paper, $500 in benefits. But the airline credit requires you to actually fly with that specific airline, and the travel credits cap at certain merchants. You don’t get the full $500 in liquidity you’d get from $550 in straight points.
The hidden cost is opportunity cost. That annual fee compounds across years. Pay $250 annually for four years, and you’ve paid $1,000 plus interest on the float. You only break even if your bonus points plus earned points exceed your cumulative fees by at least 20 percent. Most people hit this breakeven point in year one due to the sign-up bonus, then lose money in years two and three because ongoing earning doesn’t match the fee. Downgrade or close the card before year two renews unless your annual spend in bonus categories genuinely exceeds the fee by a margin worth the administrative friction.
The Arbitrage Protocol: Exploiting Point Valuations For Your Dream Honeymoon
Transfer Bonuses And Redemption Sweet Spots
You’re reading this because you want proof that points aren’t just breakeven math—they’re actual currency manipulation if you know where to look. Arbitrage is economics jargon for buying low and selling high in different markets. In points, it means moving currency from one valuation zone to another before redeeming. Most people never do this. They cash points out at face value and wonder why they got 1 cent per point instead of 3.
The real leverage sits in transfer bonuses and partner airline sweet spots. Chase Sapphire Preferred transfers Ultimate Rewards to 20-plus airlines at a 1:1 ratio, but those airlines don’t value all redemptions equally. American Airlines charges 40,000 points for a domestic flight one week, 50,000 the next. Partner transfer bonuses shift constantly. Amex Platinum occasionally offers 35% more points when you transfer to specific airlines in specific windows. You catch these, you move points during the bonus window, then book the underpriced redemption.
- Airline transfer partner sweet spots: Some partners offer consistently lower redemption rates on popular routes. Qatar Airways, for example, prices many long-haul flights at 65,000 points instead of the 70,000-plus you’d see on US carriers. Map your honeymoon destination against partner pricing first.
- Quarterly bonus windows: Credit card issuers announce transfer bonuses sporadically. Amex runs 30-50% bonuses on selected airlines 2-4 times yearly. Sign up for alerts from major issuers to catch when your preferred partner enters a bonus window.
- Off-peak redemption rates: Airlines price differently by season and day of week. Booking Thursday to Sunday honeymoon flights costs 10,000-15,000 more points than the same route on Tuesday. Build flexibility into your dates if possible.
- Stopover and open-jaw routing: Some airline programs let you stop in one city free, then fly to another. This costs no extra points but would cost cash separately. Program rules vary—check partner terms before transferring.
- Airline devaluation cycles: Airlines lower point values every 18-36 months on popular routes. If you have 300,000 points sitting idle, transfer them to a partner now rather than waiting. Waiting is a slow loss.
The mechanism is simple: valuations drift. You exploit the drift by moving points into undervalued partners before the gap closes. Capture this gap before your honeymoon date locks in. Wait, and the sweet spot disappears.
When To Pay Cash Instead Of Burning Points
Most advice says redeem points whenever possible. That’s backwards. You should compare the effective cents-per-point value of redemption against your actual cost of cash, then choose the option that preserves optionality. Economics calls this opportunity cost. Your points have an opportunity cost too. Burning 100,000 points for a flight you value at $1,200 works only if you couldn’t have used those points for something worth $1,400 later.
Sometimes paying cash preserves points for higher-value redemptions. If you’re eyeing a five-star resort in Bali that costs 300,000 points or $4,500 cash, and you only have 200,000 points, pay cash for the flight and save your points. A points-heavy honeymoon beats a points-poor one. The real trap: people redeem low-value flights at 1.2 cents per point, then run out of points for the 5-cent-per-point resort stay. This is backwards sequencing. Calculate the average cents-per-point value for your entire honeymoon first, then work backward to determine what you actually redeem versus pay for. Points should fund your highest-value leg, not your lowest.
The Velocity Method: Accelerating Your Honeymoon Savings With Strategic Spending
Matching Spend To Card Categories
You want to believe there’s a secret hack that compounds your points faster than everyone else. There isn’t. The mechanism is simpler: you’re leaving money on the table by using the wrong card for the wrong transaction. This is basic economics applied to rewards, and most couples ignore it completely.
Credit card issuers engineered category bonuses to track your behavior. Grocery stores, gas stations, dining, travel purchases, and everything else get slotted into different tiers. A 5x multiplier on groceries beats a 1x flat-rate card by a factor of five. If you spend $800 monthly on groceries before your honeymoon year, that’s an 800-point swing per month just by holding the right plastic. Stack that across twelve months and you’re looking at a free flight tier nobody earned through passivity.
The work here is inventory and routing. Map your existing spend across categories for the past three months. Identify which card multiplies each bucket. Then execute: groceries on the 5x card, gas on the 2x card, dining on the bonus card. This kills the romance of the hunt, but it kills the gap between your points and someone who actually planned. Most people don’t do this. They carry one card and call it strategy.
Manufactured Spending And Its Real Cost
Everyone whispers about manufactured spending like it’s a loophole. It’s not. It’s a tactic with friction, risk, and rapidly diminishing returns that most people overestimate. The advice you’ll hear is either “do it aggressively” or “don’t touch it.” Both miss the actual mechanism.
Manufactured spending works by converting cash into points through intentional transactions that don’t reflect real consumption. The classic version: buy money orders at a grocery store that codes as a purchase, then deposit them. You hit the 5x multiplier on something that wasn’t actually a grocery transaction. The cost isn’t the transaction itself. The cost is time, the risk of account shutdown if you trigger fraud filters, and the fact that most card issuers have tightened coding over the last five years. What worked in 2015 works differently now.
The real question isn’t whether manufactured spending is possible. It’s whether the points per hour justify the execution. If you can manufacture $5,000 in spend in four hours but earn only 25,000 points, that’s 6,250 points per hour. A flight redemption at one cent per point values that at $62.50 per hour. After accounting for risk, mental load, and potential account damage, most honeymoon planners hit better ROI just optimizing category spend and hitting sign-up bonuses on new cards. The tactic exists. The honeymoon timeline usually doesn’t favor it. Only deploy this if you have months to buffer against clawbacks and genuinely free time.
The Network Effect: Maximizing Your Honeymoon Wedding Fund Through Partner Programs
Transfer Points Into Airline And Hotel Programs
You want to believe your credit card points are worth face value, but they’re not. The real move is treating points like currency that gains value only when converted into specific loyalty ecosystems where airlines and hotels set their own redemption rates. Most people leave points sitting idle because the math looks complex, when it’s actually simple: transfer to programs with proven sweet spots where off-peak inventory exists and point costs stay reasonable.
The transfer mechanism works because loyalty programs need liquidity from credit card companies to fund their operations. When you move Chase Ultimate Rewards into United Airlines, for example, you access United’s award calendar directly. One-to-one transfers preserve purchasing power far better than redeeming for generic travel through the credit card portal. The portal redemption rate usually undercuts what you’d pay transferring to a partner by fifteen to thirty percent.
Status Tiers Unlock Pricing Advantages
Status in loyalty programs works like leverage in economics: your position in the system determines the resources available to you. Elite status doesn’t give you more points, it gives you access to pricing that non-members can’t see and the ability to confirm seats that would otherwise require more points. A Platinum member on American Airlines burns fewer points per redemption than a non-member on the same route because the program weights elite status into the award pricing algorithm.
You build status through spending velocity, not point accumulation. Credit card spend and actual travel miles both count toward annual thresholds. Once you hit status, book honeymoon flights and hotels during promotional windows when programs release limited award inventory at lower point costs, then use elite perks like complimentary upgrades or room upgrades to amplify the value beyond the redemption itself. Apply for elite status targeting before your wedding date so you hit thresholds with time for booking windows to open.
The Opportunity Cost Fallacy: When “Free” Travel Isn’t Free
What Your Points Actually Cost
You’re drawn to this because you want to believe you’ve outsmarted the system. Here’s what nobody says plainly: points have an opportunity cost that most people never calculate. In economics, opportunity cost measures what you give up when you choose one option over another. With travel rewards points, the hidden cost is the spending you had to do to earn them in the first place.
Credit card companies don’t hand out points. You paid for them through annual fees, higher merchant prices they negotiate into vendors, or spending on a card you wouldn’t have otherwise used. A 50,000-point signup bonus on a card with a $95 annual fee isn’t free if you wouldn’t have opened that card without the honeymoon goal. The airline or hotel already priced that cost into their economics. You’re just seeing the illusion of a discount.
Math That Actually Matters
Most people value points at 1 cent each. That’s lazy. Your actual return depends on what you redeem for and when. A business-class international flight seat worth $8,000 retail but costing 150,000 points gives you a 5.3-cent valuation. A $150 hotel night costing 60,000 points gives you 0.25 cents. The gap is massive, and most honeymoon planners don’t do this math before booking.
Calculate your true ROI by dividing the retail value of what you’re redeeming by the total points spent plus all fees paid to earn those points. If you spent $2,000 in spending to earn 100,000 points and paid $475 in annual fees over two years, your cost basis is $2,475. A honeymoon package worth $6,000 on points means your actual return is 142 percent, not the 600 percent the points website claims. Work backward from the honeymoon destination you want, price it both ways, then decide.
Architecting Your Honeymoon: A Blueprint For Requesting Money For Honeymoon Funds
The Direct Ask Without The Cringe
You’re worried people will judge you for asking. That’s the real issue here, not the logistics. The mechanism is simple: most people don’t know how to give money gracefully, so they wait for permission. You’re actually solving their problem by making the ask explicit and low-friction.
Stop the indirect hints. No registry mystery. No vague “we’re saving up” statements that leave relatives guessing. Create a single, clear destination where people can contribute cash directly to your honeymoon fund. A direct ask removes ambiguity and signals confidence, not entitlement. People respect clarity.
The Dedicated Fund Platform
Registry psychology doesn’t apply here. You’re not asking people to buy objects from a store. You’re creating a financial mechanism, and the platform is your infrastructure. Platforms like Honeyfund, GoBrideGo, and Zola let you set a target amount, show progress, and accept contributions without the awkwardness of a bank account number.
The platform does three things: it legitimizes the request, it tracks contributions so you can thank people properly, and it removes you from the transaction entirely. Set up the fund 6 to 8 weeks before your wedding. Link it from your wedding website and mention it once in a conversation with close family. Let the platform handle the rest. You control when and how to access the money.
The Redemption Paradox: Unlocking Premium Experiences With Less
Where Business Class Actually Makes Sense
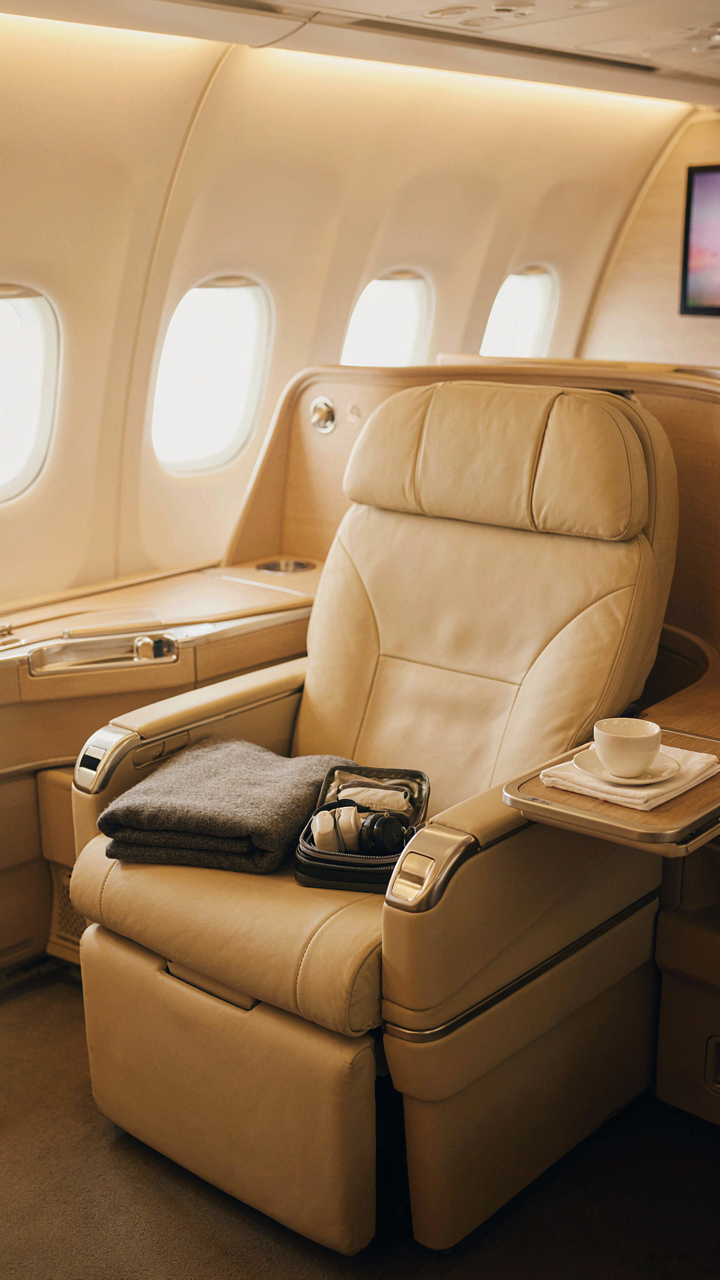
You want the status symbol without the price tag. That’s the real reason you’re reading this. Here’s the mechanism: airlines price business class based on demand and route, not cost. A transatlantic business seat costs the airline maybe 3x what economy costs to operate, but sells for 6-10x the price. Points redemptions bypass this markup entirely. You redeem the same seat for a flat points cost regardless of the airline’s pricing psychology on that day.
The sweet spot sits on long-haul routes where business class cabins exist. Transatlantic and transpacific flights to your honeymoon destination are the play. Most premium cabin redemptions cost 70,000 to 120,000 points per person one way on major carriers. Economy costs 25,000 to 50,000 points. The upgrade value justifies itself immediately on flights over eight hours when you actually sleep before arriving. Shorter routes offer worse point-to-experience ratios, so skip business redemptions under six hours.
The Mistakes Nobody Warns You About
Redemption flatlines happen because travelers fail to check availability windows. Most systems only display five to eleven months out. Airlines release business class inventory in waves, and you’ll miss premium cabins by booking too early or too late. The real cost is not the points you spend, it’s the dates you lose flexibility on because inventory disappeared. Stop booking your honeymoon dates first, then hunting points availability. Reverse it: find the best redemption windows, then plan your trip around what the calendar actually offers.
- Booking too far ahead: Premium cabin inventory releases gradually. Checking at 330 days out leaves you staring at economy-only options. Peak availability typically lands 2-3 months before departure.
- Confusing point values with actual cost: A 100,000 point redemption feels expensive until you price the cash equivalent at $1,500-$2,000. Points feel abstract. Pricing the alternative clarifies whether you’re getting leverage or burning inventory on mediocre value.
- Ignoring fuel surcharges on certain programs: Some carriers add cash surcharges to premium redemptions even when you pay points. These fees run $150-$400 per person. They’re real costs disguised as taxes and don’t vanish when you use points.
- Redeeming for hotels at published rates: Hotel programs price out redemption nights based on the cheapest available room rate, not peak pricing. You redeem for base rooms, not upgrades. Cash rates show inflated honeymoon pricing that points don’t access anyway.
- Splitting one-way tickets instead of round-trips: Some programs charge fewer points for round-trip bookings than two separate one-ways combined. Calculate both structures before confirming. The math flips based on carrier and distance.
The protocol is simple: lock in your destination first, then search for business class availability on your preferred dates across all carriers your points can access. When you find seats, book that instant. Availability on premium cabins vanishes within hours of release, especially for popular honeymoon routes. Don’t deliberate. Confirm the redemption immediately, then build your itinerary around the flights you secured.
The Post Honeymoon Audit: Optimizing Your Future Travel Rewards Strategy
Did Your Cards Actually Pay Off
You want to know if you won this game or just got lucky. That’s the real question. The mechanism nobody names plainly: most people spend more to hit bonuses than they would have anyway, then convince themselves the points justified it. Economics calls this the substitution effect, but for travel rewards it’s just spending disguised as profit.
Pull your statements from the past twelve months. Calculate the annual fees you paid. Subtract the cash value of the points you actually redeemed for the honeymoon. If that number is negative, your cards cost you money. If positive, measure it against what you would have spent on that honeymoon without points. That gap is your actual return. Most people never do this math because they don’t want to know the answer.
The Churn Cycle That Actually Works
Forget the common advice about cycling cards every two years like a robot. Churning cards works because sign up bonuses are the only mathematically guaranteed profit in the rewards ecosystem. You’re not earning points faster on purchases, you’re capturing bonuses that have real dollar values printed on them.
The real protocol: apply for a card only when you have planned spend that meets the minimum spend requirement. Hit that minimum through existing expenses or timed purchases you’d make anyway, never forced spending. Redeem the bonus. Wait until that card’s annual fee posts, then cancel before the second year. Reapply to the same card in twelve to eighteen months when the bonus resets. Issuers allow this because acquisition costs are lower than retention costs. Your job is becoming a disciplined operator, not a points collector.
The Real Obstacle Is Not Understanding Points; It Is Your Aversion To Strategic Financial Engineering
Most people sabotage their honeymoon before it starts. They treat points like spare change instead of currency. Stop waiting for the “perfect” redemption. Open a rewards credit card today, spend what you already planned to spend, and book your honeymoon in three months instead of five years. Your competitors are already doing this. The only question is whether you’ll join them or convince yourself you’re not a “points person.” You absolutely are. Everyone is.